







Riverhead Town failed to record a $3.57 million federal grant transaction and did not adequately oversee how the money was spent, according to a 2025 audit completed by the town’s independent auditing firm.
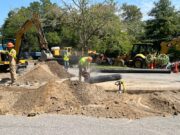
The federal Environmental Protection Agency grant, was congressionally directed funding from the 2022 Bipartisan Infrastructure Bill. The money helped offset the town’s cost to extend public water to 64 homes in Manorville whose private wells were contaminated by various chemicals, including PFAS. The town’s grant money was paid to Suffolk County Water Authority, which installed the water mains and supplies water to those homes, pursuant to a 2022 agreement with the water authority.
The auditors’ findings do not establish that money was missing or misspent. They identify failures in the town’s accounting, reporting and oversight that could allow errors or improper expenditures to go undetected, according to the audit report.
The external auditors’ report on the town’s 2025 financial statements found no material weaknesses and concluded that revenue outpaced expenses last year, adding nearly $4.9 million to the town’s general fund balance, which grew to $33.3 million.
See separate story: Audit: Riverhead’s general fund balance grows to $33.3 million as revenue outpaces spending
PKF O’Connor Davies, the town’s independent auditing firm, classified three procedural failures as material weaknesses—the term auditors use for serious deficiencies in the safeguards intended to prevent or detect significant accounting errors or failures to comply with grant requirements.
Auditors found the town failed to record receipt of the $3.575 million EPA grant as well as the corresponding payment to the water authority. The transaction was also omitted from the town’s schedule of federal expenditures.
As a result, both federal revenue and spending were understated by $3.575 million. The completed audit includes the transaction.
The auditors separately found that reports submitted to EPA were inaccurate and required multiple revisions. The town lacked written procedures for preparing and checking the reports and relied on EPA reminders for deadlines and requirements.
The town also did not adequately review the water authority’s expenses before including them in payment requests, lacked procedures for monitoring its purchasing and omitted required grant provisions from its agreement with the authority.
Although Riverhead checked that the water authority had obtained annual audits, that did not fulfill the town’s oversight responsibilities, the audit report said.
The auditors made written recommendations for corrective action for each of the material weaknesses identified.
In written responses dated Aug. 7 and included in the single audit document, the town agreed with all three findings and described a corrective action plan for each. Some of the recommended corrective actions were already implemented, the town said. The others would be implemented by Sept. 30.
Community Development Director Dawn Thomas, whose office is responsible for the town’s grant applications, administration and reporting, said this was the first time the town has ever obtained a grant through this grant program. She acknowledged that procedures were not documented as required, but said the proper procedures were followed.
“It’s a small town, it’s not a big entity, and sometimes the way we do things wasn’t to the liking of the auditors who want everything to be incredibly documented,” Thomas said.
“The auditors also were concerned that we didn’t verify all of those submissions for reimbursement for Suffolk County Water for eligibility under the grant, but we knew they were eligible. We didn’t have a written verification of that, but everything was paid and therefore establishes that it was eligible,” Thomas said.
The town has now created the written policies and procedures the auditors wanted.
Thomas said when the town missed a deadline for one of the reports, “we were in communication with the EPA, who was fine with what we were doing. We have a good working relationship with them,” she said.
As for the grant itself, she said, “Everything’s on track with the grant. Everything’s fine with the grant.” Thomas added that the federal money was paid to the town, reimbursing it for its advance outlay of the funds for the extension.
The separate audit, known as a single audit, is mentioned in PKF’s independent report 2025 audit dated Aug. 7. In a section titled “Other Reporting Required by Government Auditing Standards.” There, PKF discloses the existence of the single audit report, also dated Aug. 7, but does not state what the separate report pertains to. It does state that the separate audit report is “an integral part of an audit performed in accordance with Government Auditing Standards in considering the Town’s internal control over financial reporting and compliance.”
The single audit report was not mentioned in the Sept. 1 resolution unanimously adopted by the board accepting PKF’s audited financial statements and report. The auditor’s report that was attached to the Sept. 1 resolution did not include the single audit report.
Neither audit has been publicly discussed by the Town Board or posted on the town’s website.
RiverheadLOCAL retrieved the single audit report from the website of the Federal Audit Clearinghouse.
The town’s independent auditors have typically been invited to a public Town Board work session to discuss the annual audit with the board. That has not happened this year. Supervisor Jerry Halpin, who took office in January, said he had been unaware of those meetings. He also said he was unaware that the audits had not yet been posted on the town’s website. He was unclear about whether he knew the single audit was not attached to the Sept. 1 resolution.
Although he took office after the period covered by the audit, the supervisor as the town’s chief fiscal officer is now responsible for addressing the findings and explaining the town’s response. Halpin said in an interview yesterday he is confident that the auditors’ concerns have been or are being properly addressed by the town’s financial administrator and community development director.
The survival of local journalism depends on your support.
We are a small family-owned operation. You rely on us to stay informed, and we depend on you to make our work possible. Just a few dollars can help us continue to bring this important service to our community.
Support RiverheadLOCAL today.
